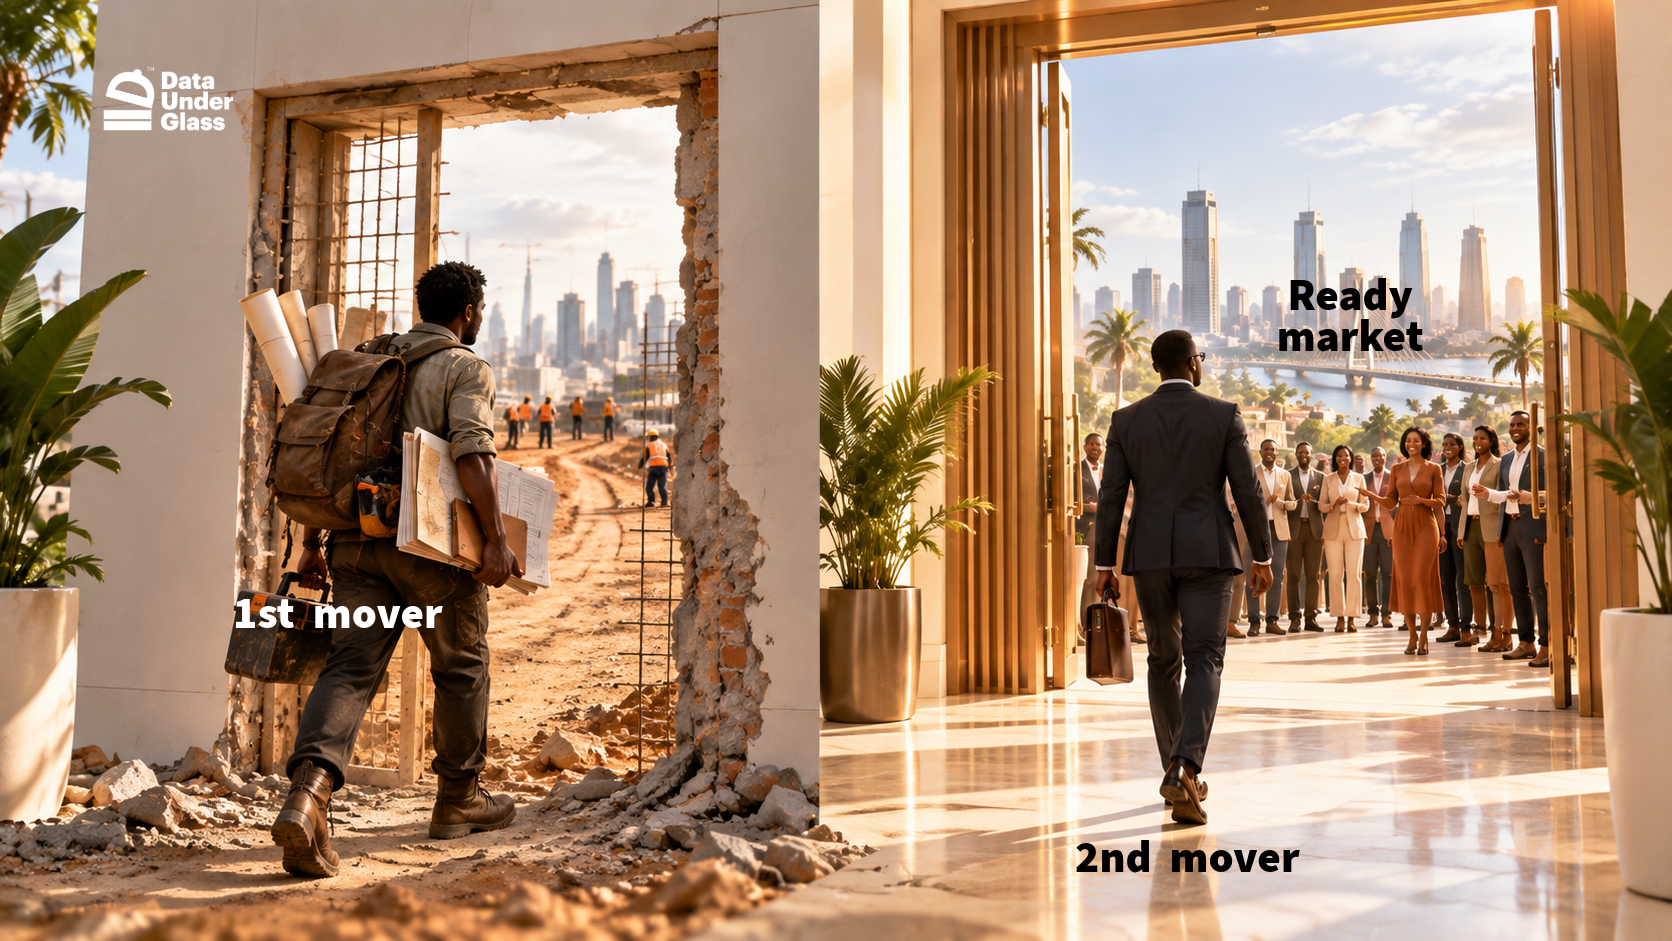
A Toronto-based identity-verification SaaS company opens a Lagos office before Nigerian buyers have a funded compliance mandate (an illustrative scenario, not a case study). Pilots run and workshops fill, but no procurement budget follows. Then the rules land: the Central Bank of Nigeria (CBN) revised its BVN framework in October 2021 and, in December 2023, made a BVN or NIN mandatory for Tier 1 accounts and wallets. Budgets appear, and better-funded rivals arrive. What failed was not the product. It was the assumption that early presence converts into ownership.
— Anderson Oz’
From the Operator’s Desk
What Leadership Believes
Arriving first would lock in enterprise relationships and build a brand moat.
What Broke
- Pilots stalled because buyers had no mandate-backed budget line.
- Cash funded market education and regulatory learning that any rival could observe.
- No switching costs, proprietary data or distribution control accumulated.
- When enforcement arrived, buyers asked which vendor, favoring the best-funded bidder.
The Reality: Demand was gated by enforcement, not product quality. Registrations jumped once a deadline existed, and scale compounded afterward.
The Lesson: Do not fund market education with equity when a regulatory or infrastructure trigger will create the budgets for you.
The Evidence Stack
- 854,267: New BVN registrations in two months to July 2024, primarily attributed to the CBN’s December 2023 account-restriction directive. A deadline turned an optional task into an urgent one.
- 51.9M → 67.8M: BVN enrolments, 2021 to 2025, per NIBSS data reported by The Guardian Nigeria. This is the installed base a late entrant sells into.
- 297.29M → 368.92M: Bank accounts linked to BVNs in 2025, up about 24%, per the CBN’s 2025 Annual Report as reported by PM News. Scale followed the rulebook.
- ρ = 0.10: Average correlation between early entry and performance across 22 international-entry studies, per Dykes and Kolev. Positive, but thin and conditional.
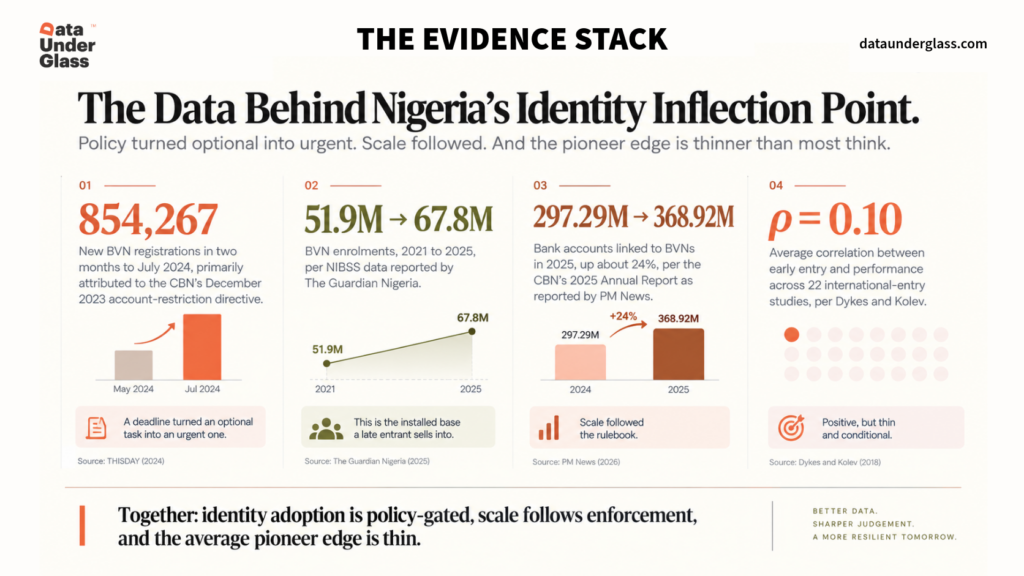
Together: identity adoption is policy-gated, scale follows enforcement, and the average pioneer edge is thin.
Flagship Insight: The Market Readiness Externality
In an immature market, the pioneer pays to make demand legible, and that learning is not exclusive. Four layers decide who captures its value.
1. The Regulatory Trigger. Before enforcement, buyers can delay; after it, urgency changes. Nigerian enrolments surged once a deadline existed, while a Toronto vendor selling KYC earlier heard “not yet.”
2. The Information Spillover. Integrations tested, prices explained and objections mapped are visible to rivals. A 2023 European Economic Review model finds first-mover advantage emerges through preemption, then second-mover advantage prevails as firms learn from entry. Vidal and Mitchell argue the celebrated advantage largely reflects survival bias.
3. The Infrastructure Ceiling. The same December 2023 circular made BVN and NIN databases the primary onboarding source, so an identity vendor’s rollout speed depends on those rails, not its sales team.
4. The Capital Reversal. Once uncertainty falls, capital becomes more productive. A Management Science meta-analysis found market-share studies far likelier to detect a pioneer advantage than profitability or survival studies, so judge pioneers on economics, not share.
What’s Actually Working
1. Gate growth capital to named enforcement events. Release expansion budget only when a specific regulatory or infrastructure trigger is live; until then, cap spending at a small learning budget.
2. Convert interest into paid evidence. Charge for pilots and prioritize buyers with a funded compliance line, so interest becomes budget data.
3. Pre-negotiate your exit. Identify well-capitalized late entrants as potential partners or acquirers, and set the trigger for that talk in advance.
Steal This: The Headcount Audit
1. Trigger map (Days 1–2): List every regulation, circular or infrastructure milestone that makes your product required. Date each and mark it enforced or not.
2. Budget census (Day 3): For every active prospect, record whether a funded budget line exists. Count paid versus unpaid pilots.
3. Inheritance test (Days 4–5): Write what a well-funded rival entering in six months would inherit from you. Circle what is protected.
4. Gate memo (Days 6–7): Draft a one-page rule stating which triggers release, hold or reverse growth capital. Get leadership sign-off.
Field Intelligence
Signal
- Tying expansion capital to named enforcement or infrastructure events.
- Tracking regulatory milestones alongside pipeline metrics.
- Building switching costs, data and distribution before the market tips.
- Treating well-capitalized late entrants as potential partners or buyers.
Noise
- “We have first-mover advantage.”
- “Nobody else is doing this.”
- Treating buyer enthusiasm as an allocated budget.
- Assuming technical feasibility means commercial readiness.
Bottom Line
Summary: Pioneers in immature markets pay for learning that rivals inherit, so timing decides who captures the value.
Reality: Operators who understand it spend when budgets exist and hold when they don’t. The rest keep funding education, then meet better-capitalized rivals just as demand arrives.
Hard Truth: If your only advantage is that you arrived first, you didn’t build a category; you built your competitors’ launch pad.